1. What Is Financial Stress and Mental Wellness?
Money is part of everyday life.
You use it to pay for food, housing, transportation, education, healthcare, communication, entertainment, family responsibilities, and countless other needs.
Because money touches so many areas of life, financial pressure can affect more than your bank account.
It can affect your thoughts.
Your emotions.
Your sleep.
Your relationships.
Your lifestyle choices.
Your confidence.
And your ability to focus on the future.
This is where Financial Stress and Mental Wellness become closely connected.
Financial stress can come from many different situations. You might be worried about debt, inconsistent income, unexpected expenses, rising costs, family responsibilities, job uncertainty, saving for the future, or simply feeling that your money disappears before the month ends.
Not every financial challenge can be solved through budgeting alone.
Income, employment, housing costs, healthcare expenses, economic conditions, family responsibilities, and access to resources can all shape a person’s financial reality.
That is important to acknowledge.
Financial wellness should never become a way of blaming people for circumstances outside their control.
Instead, financial wellness is about identifying the areas you can influence and creating healthier systems around them.
The Consumer Financial Protection Bureau describes financial well-being in terms of having control over day-to-day finances, being able to absorb a financial shock, making progress toward financial goals, and having freedom of choice in life.
That definition is useful because it shows that financial wellness is not simply about becoming wealthy.
It is about creating greater stability, confidence, and choice.
And when money feels more manageable, your overall lifestyle can become more manageable too.
2. Why Money Can Affect More Than Your Bank Account
Financial stress rarely stays in one area of life.
Financial Stress and Mental Wellness are connected because ongoing money uncertainty can occupy attention that could otherwise be used for work, relationships, rest, and everyday activities.
Imagine receiving an unexpected expense when you already have several bills due.
You may start thinking about how you will cover it.
Then you may worry about your savings.
Then you may think about work.
Then you may become distracted during the day.
Later, you may find yourself lying awake thinking about money.
The financial problem may have started with a number.
But the emotional experience can become much larger.
Money worries can create mental pressure because they often involve uncertainty.
Will I have enough?
What if something unexpected happens?
Can I afford this?
Am I falling behind?
What happens if my income changes?
These questions can consume mental energy.
The American Psychological Association has documented money and economic concerns as significant sources of stress, while the World Health Organization recognizes that economic and social conditions can influence mental health and wellbeing.
This does not mean every financial challenge causes a mental health condition.
It means that financial circumstances are one of the many factors that can shape stress and wellbeing.
That distinction matters.
If you are experiencing serious or persistent anxiety, depression, sleep problems, or other mental health symptoms, financial planning alone may not be enough. Professional mental health support can be an important part of your care.
At the same time, creating healthier financial systems can remove some avoidable uncertainty from everyday life.
That is the opportunity.
3. The Connection Between Money Habits and Lifestyle
Your money habits influence the choices available to you.
Consider a few examples.
If you regularly spend more than you earn, you may have less flexibility when an unexpected expense appears.
If you do not track recurring expenses, you may underestimate how much of your income is already committed.
If you have no savings cushion, a financial surprise may feel more threatening.
If you constantly compare your lifestyle with people online, you may feel pressure to spend money to keep up.
If you avoid financial conversations, problems can remain hidden until they become harder to manage.
These are not reasons to feel guilty.
They are opportunities to become more aware.
A healthier financial lifestyle begins with understanding what is happening rather than avoiding it.
You do not need a perfect budget.
You need a system you can actually use.
You do not need to eliminate every enjoyable purchase.
You need to understand your priorities.
You do not need to become obsessed with money.
You need to make money serve your life instead of allowing financial uncertainty to dominate it.
That is one of the most practical connections between Financial Stress and Mental Wellness.
Better financial awareness can create more clarity.
More clarity can make decisions easier.
And easier decisions can reduce some forms of avoidable financial overwhelm.
4. Why Financial Wellness Is Part of Overall Wellness
Wellness is not limited to what happens inside a gym.
It includes the systems that support your everyday life.
Your physical health matters.
Your mental health matters.
Your emotional wellbeing matters.
Your relationships matter.
And your financial health matters too.
Financial stress can influence lifestyle decisions.
A healthier approach to Financial Stress and Mental Wellness recognizes that financial habits should support your overall quality of life rather than create additional pressure.
For example, someone experiencing financial pressure may postpone certain activities, avoid social events, delay health-related spending, work additional hours, or sacrifice rest.
Again, these decisions are not always optional.
Many people face genuine financial constraints.
But this is precisely why financial wellness belongs in a broader wellness conversation.
The goal is not to pretend money problems do not exist.
The goal is to develop practical skills and supportive habits that help you navigate them.
Financial wellness can include:
- Knowing where your money goes
- Understanding your recurring expenses
- Planning for upcoming obligations
- Creating realistic savings goals
- Managing debt intentionally
- Building financial confidence
- Avoiding unnecessary financial pressure
- Preparing for unexpected expenses
- Making values-based spending decisions
- Learning continuously
The Consumer Financial Protection Bureau emphasizes that financial well-being is broader than income or net worth.
Two people can earn similar incomes and experience very different levels of financial wellbeing.
That is because financial confidence, obligations, habits, security, goals, and freedom of choice all matter.
Your financial life is personal.
Your wellness plan should be personal too.
5. 10 Powerful Financial Stress and Mental Wellness Strategies
You do not need to completely transform your finances overnight.
In fact, trying to change everything at once can create even more pressure.
A better approach is to focus on small, practical systems that improve clarity and confidence.
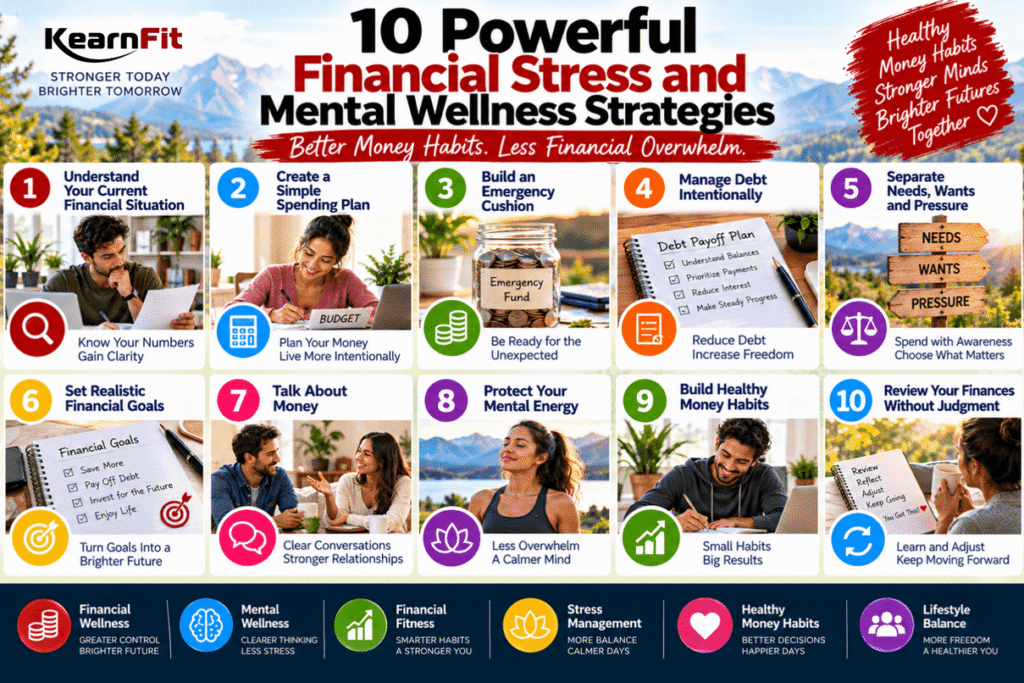
Here are 10 strategies to help create a healthier relationship between your money habits and your overall lifestyle.
6. Strategy #1: Understand Your Current Financial Situation
The first step is awareness.
You cannot create a useful financial plan if you do not know what is happening.
Start with the basics.
Awareness is an important first step in Financial Stress and Mental Wellness because knowing what is happening can make financial decisions feel more manageable.
How much money comes in each month?
What expenses are fixed?
What expenses change?
What subscriptions are active?
What debt payments are due?
How much are you saving?
What financial obligations are coming soon?
You do not need a complicated spreadsheet.
A simple overview can be enough to start.
Create four categories:
Income
Money coming in.
Essential Expenses
Housing, food, utilities, transportation, healthcare, and other necessary costs.
Financial Commitments
Debt payments, savings contributions, insurance, and other obligations.
Flexible Spending
Entertainment, shopping, dining out, hobbies, and optional purchases.
The purpose is not to judge yourself.
It is to see reality clearly.
Avoiding your finances may feel easier for a few minutes, but uncertainty can become more stressful over time.
Awareness gives you something to work with.
If the numbers are difficult, start with one account or one week of spending.
You do not have to understand your entire financial life in one afternoon.
7. Strategy #2: Create a Simple Spending Plan
A budget does not have to feel restrictive.
Think of it as a plan for your money rather than a punishment for spending it.
Your spending plan should reflect your real life.
Start with your income.
Then identify essential expenses.
Next, account for financial goals and obligations.
Finally, create space for enjoyable spending.
That last category matters.
A plan that leaves no room for anything enjoyable may become difficult to maintain.
Your goal is not to eliminate pleasure.
Your goal is to make your spending intentional.
For example, instead of making several unplanned purchases throughout the week, you might choose one or two experiences that genuinely matter to you.
Instead of buying something because it is trending, you can ask:
Do I actually want this?
Does it fit my priorities?
Will I still value it later?
Am I buying it because I need it, enjoy it, or feel pressured?
These questions create a pause between emotion and action.
That pause can be valuable.
8. Strategy #3: Build an Emergency Cushion
Unexpected expenses are part of life.
Cars need repairs.
Devices stop working.
Health expenses can appear.
Travel may become necessary.
Employment circumstances can change.
You cannot predict every financial surprise.
But you can prepare for some of them.
An emergency fund or financial cushion can help create greater resilience.
The amount you need depends on your circumstances.
Building financial resilience can support Financial Stress and Mental Wellness by giving you a greater sense of preparation when unexpected expenses appear
Instead of focusing immediately on a perfect number, focus on building the habit.
Start small.
Set aside a manageable amount regularly.
Automate it if that works for your situation.
Increase it when your circumstances allow.
The goal is to create a buffer between an unexpected expense and a financial crisis.
This can also support mental wellbeing.
When you know you have at least some resources available for unexpected situations, certain financial surprises may feel more manageable.
Do not compare your emergency fund with someone else’s.
Your starting point is your starting point.
Progress matters.
9. Strategy #4: Make Debt Management More Intentional
Debt can become a significant source of financial pressure, particularly when payments are difficult to manage or balances continue growing.
The first step is not panic.
It is clarity.
List your debts.
Record balances, interest rates, minimum payments, and due dates.
Then determine what approach is realistic for your situation.
Depending on your circumstances, you may choose to prioritize higher-interest debt, focus on smaller balances for motivation, or seek professional financial guidance.
If debt feels overwhelming, do not rely on avoidance.
Realistic goals are central to Financial Stress and Mental Wellness because achievable progress can build confidence without creating unrealistic financial pressure.
Ignoring statements does not make the debt disappear.
At the same time, do not let debt become your identity.
Having debt does not mean you are a failure.
It means you have a financial situation that needs attention.
If you are dealing with complex debt, legal concerns, or serious financial hardship, consider seeking advice from an appropriately qualified financial counselor or professional.
The goal is progress.
Not punishment.
10. Strategy #5: Separate Needs, Wants, and Pressure
Modern life makes spending incredibly easy.
A product can be purchased in seconds.
A meal can be delivered in minutes.
A subscription can renew automatically.
A social media post can make a lifestyle look normal even when it is financially unrealistic for you.
This creates a challenge.
Not every desire is a need.
And not every desire is a bad thing.
Enjoyment is part of life.
The goal is to understand the difference.
Try dividing purchases into three categories:
Needs: Essential expenses required for everyday living.
Wants: Things that improve enjoyment but are not essential.
Pressure: Purchases influenced primarily by comparison, fear of missing out, status, or other people’s expectations.
That third category deserves attention.
Ask yourself:
Would I still want this if nobody else could see it?
That question can reveal how much of your spending is driven by genuine preference versus social pressure.
Financial wellness is not about never spending money.
It is about spending with awareness.
11. Strategy #6: Create Financial Goals That Feel Realistic
Big financial goals can be inspiring.
But vague goals can also create stress.
Realistic goals are central to Financial Stress and Mental Wellness because achievable progress can build confidence without creating unrealistic financial pressure.
Instead of saying:
“I need to get better with money.”
Create something specific.
For example:
- Save a certain amount each month
- Build an emergency cushion
- Pay down a specific debt
- Review subscriptions
- Track spending weekly
- Increase savings gradually
- Create a plan for a major upcoming expense
- Learn one new financial skill each month
Make the goal measurable.
Then break it into smaller actions.
If your long-term goal feels overwhelming, focus on the next step.
One month of better habits is still progress.
One improved decision is still progress.
One avoided unnecessary expense is still progress.
One conversation about money is still progress.
Your financial life is built through repeated decisions.
That is why consistency can be more powerful than dramatic short-term changes.
12. Strategy #7: Stop Avoiding Money Conversations
Money can be uncomfortable to discuss.
People may fear judgment.
They may feel embarrassed about debt.
They may worry about income differences.
They may avoid conversations with partners or family members because they expect conflict.
But silence can create its own problems.
If you share financial responsibilities with someone, communication can be essential.
Talk about:
- Financial priorities
- Household responsibilities
- Major expenses
- Savings goals
- Debt
- Lifestyle expectations
- Family responsibilities
- Long-term plans
You do not need to reveal every private financial detail to everyone.
But the people directly affected by shared financial decisions should generally have opportunities for honest, respectful conversations.
Use neutral language.
Instead of:
“You are terrible with money.”
Try:
“I think we should look at our spending together and decide what matters most.”
The goal is not blame.
It is teamwork.
13. Strategy #8: Protect Your Mental Energy From Financial Overload
You can become so focused on money that money starts occupying every part of your mind.
Checking your account repeatedly.
Reading financial news constantly.
Protecting your attention is an important part of Financial Stress and Mental Wellness, especially when financial information and worries can easily become part of your everyday mental routine.
Comparing investments.
Thinking about expenses before bed.
Worrying about future scenarios.
Refreshing apps.
Running through hypothetical problems.
Financial awareness is healthy.
Financial obsession can become exhausting.
Create boundaries around financial thinking.
For example, choose one weekly time to review your budget.
Use automatic payments and transfers where appropriate.
Keep important financial information organized.
Avoid making major financial decisions while highly emotional.
Give yourself permission to step away after completing your review.
You do not need to think about money every minute to be responsible with money.
Mental rest matters too.
The CDC notes that long-term stress can contribute to worsening health problems, making everyday stress management an important part of wellbeing.
Money management should support your life.
It should not consume your entire life.
14. Strategy #9: Build Healthy Money Habits With Your Lifestyle
Financial habits become easier to maintain when they fit your daily routine.
For example:
Morning: Review your priorities instead of immediately checking shopping apps.
Weekly: Review spending for 15–20 minutes.
Monthly: Check recurring expenses and upcoming obligations.
Before purchases: Pause before buying nonessential items.
After payday: Move planned savings before discretionary spending.
During stressful periods: Avoid using shopping as your primary emotional coping strategy.
The goal is to reduce decision fatigue.
The more your financial system works automatically, the less mental energy you need to spend managing every small decision.
This is similar to building healthy habits in other areas.
You do not want to rely on motivation every day.
You want systems that make the healthier choice easier.
15. Strategy #10: Review Your Finances Without Judgment
One of the most powerful financial habits is learning to review your situation without attacking yourself.
Maybe you overspent last month.
Maybe you missed a savings goal.
Maybe an unexpected expense disrupted your plan.
Maybe you made a purchase you regret.
The question is not:
“Why am I so bad with money?”
Try:
“What can I learn from what happened?”
This shift matters.
Self-criticism can create shame.
Shame can lead to avoidance.
Avoidance can make financial problems harder to see.
Reflection creates a different cycle:
Notice → Understand → Adjust → Continue.
That is the same mindset that supports many other wellness habits.
You do not need to be perfect.
You need to remain engaged.
16. Financial Stress and Mental Wellness for Busy Professionals
Busy professionals often face a complicated relationship with money.
Higher income does not automatically eliminate financial stress.
Lifestyle costs may increase alongside income.
Responsibilities may increase.
Work pressure may increase.
Financial goals may become more complex.
You may also feel pressure to maintain a certain lifestyle because of your professional environment.
This is why financial wellness should not be measured only by salary.
Ask:
Does my financial lifestyle support the life I actually want?
A higher income can provide opportunities.
But if every increase in income is immediately followed by higher spending, your sense of financial security may not improve.
Avoid lifestyle inflation that happens automatically.
When your income increases, consider directing part of the increase toward:
- Savings
- Debt reduction
- Financial goals
- Emergency reserves
- Meaningful experiences
- Health and wellbeing
- Education and personal development
Your money should support your priorities.
Not simply your image.
17. Financial Stress and Mental Wellness and Sleep
Money worries often become louder at night.
Supporting Financial Stress and Mental Wellness also means creating boundaries that allow financial concerns to be addressed during the day without taking over your nighttime recovery.
During the day, work, family, technology, and responsibilities can keep your attention occupied.
At night, the distractions disappear.
That is when financial concerns may suddenly become more noticeable.
You may start calculating upcoming bills.
Thinking about debt.
Worrying about job security.
Replaying a recent purchase.
Planning how to cover an unexpected expense.
This can make it difficult to mentally switch off.
Creating a financial review routine earlier in the day may help separate money management from bedtime.
Keep a notebook nearby if financial thoughts appear at night.
Write down the concern.
Write down the next action you can take tomorrow.
Then give yourself permission to stop solving the problem for the night.
Sleep is not wasted time.
It is part of your wellbeing.
If sleep problems become persistent or significantly affect your daily functioning, consider speaking with an appropriate healthcare professional.
18. Financial Stress and Mental Wellness and Physical Health
Financial stress can influence lifestyle decisions.
When people feel overwhelmed, healthy routines can become harder to maintain.
You might skip exercise because you are working extra hours.
You might rely more heavily on convenient food because you are exhausted.
You might sacrifice recovery because you feel you cannot afford to slow down.
You might postpone certain forms of care because of financial concerns.
Some of these choices may be unavoidable.
That is why wellness advice should be realistic.
You do not need expensive wellness products to support many healthy habits.
Walking can be free.
Bodyweight movement can be free.
Preparing simple meals can sometimes be more affordable than frequent takeout.
Relaxation can happen without expensive equipment.
Social connection can happen through a conversation or walk.
The goal is to find practical options that fit your circumstances.
Financial wellness and physical wellness should work together rather than compete.
19. Financial Stress and Mental Wellness and Emotional Wellbeing
Money can trigger many emotions.
Fear.
Frustration.
Shame.
Anger.
Guilt.
Envy.
Embarrassment.
Relief.
Excitement.
These emotions are not necessarily signs that you are doing something wrong.
They are signals that money has meaning in your life.
Instead of immediately reacting to financial emotions, try identifying them.
Ask:
What am I feeling?
What triggered it?
Is this about money itself or what money represents to me?
What action is actually within my control?
For example, financial anxiety might come from uncertainty.
The solution may not be “make more money immediately.”
The first helpful action could be creating a clearer picture of upcoming expenses.
Financial guilt might come from a purchase.
The useful response could be reviewing the decision and adjusting your future spending rather than punishing yourself.
Emotional awareness can make financial decisions more intentional.
20. Financial Stress and Mental Wellness and Relationships
Money can affect relationships.
Couples may disagree about spending.
Families may have different expectations.
Friends may have different financial circumstances.
Social activities may create pressure to spend.
One person may be comfortable with expensive experiences while another is not.
Healthy relationships require honest communication about these differences.
Healthy communication can strengthen Financial Stress and Mental Wellness by reducing financial pressure, misunderstandings, and unnecessary comparison within relationships.
You do not need to explain your entire financial situation every time you decline an expensive activity.
A simple:
“That is outside my budget right now, but I would love to do something else together.”
can be enough.
Suggest alternatives:
- Coffee at home
- Walking
- Cooking together
- A free community event
- Exercise
- A picnic
- A movie night at home
- Exploring a local park
Real friendship should not depend entirely on spending power.
The strongest relationships often have room for different financial realities.
21. Financial Stress and Mental Wellness and Personal Growth
Financial wellness can create space for personal growth.
When you understand your finances, you may feel more confident making decisions about education, career development, travel, hobbies, family goals, or long-term plans.
Money becomes a tool.
Not the ultimate goal.
Personal growth also means understanding what you actually value.
Ask yourself:
What kind of life am I trying to build?
What experiences matter to me?
What do I want more time for?
What financial habits would support that lifestyle?
Maybe your priority is flexibility.
Maybe it is family.
Maybe it is entrepreneurship.
Maybe it is education.
Maybe it is travel.
Maybe it is health.
Maybe it is stability.
There is no universal answer.
Your financial habits should reflect your values.
Social media can make financial comparison difficult.
You may see:
- Luxury travel
- New cars
- Designer clothing
- Expensive restaurants
- Large homes
- Investment success stories
- Entrepreneurial lifestyles
- Constant shopping
- “Perfect” morning routines
What you usually do not see is the full financial picture behind those images.
You may not know the person’s income.
You may not know their debt.
You may not know what is sponsored.
You may not know whether the lifestyle is sustainable.
Comparison becomes dangerous when you use someone else’s visible lifestyle as a benchmark for your invisible financial reality.
Create digital boundaries.
Unfollow accounts that consistently trigger unhealthy comparison.
Be careful with financial influencers who present complicated decisions as guaranteed opportunities.
And remember:
Your financial progress does not need to look impressive online to be meaningful in real life.
23. 7 Common Money Habits That Can Increase Stress
Habit #1: Ignoring Your Numbers
Avoidance can increase uncertainty.
Habit #2: Spending to Regulate Every Emotion
Shopping can provide temporary pleasure, but it should not become your only coping strategy.
Habit #3: Comparing Your Lifestyle
Someone else’s spending does not determine your financial success.
Habit #4: Relying on Credit for Every Unexpected Expense
Credit can be useful in some circumstances, but repeated dependence can create additional pressure.
Habit #5: Making Financial Decisions While Highly Emotional
Give yourself time before major nonessential purchases.
Habit #6: Having No Financial Review Routine
You do not need to check your finances constantly, but complete avoidance is rarely helpful.
Habit #7: Treating Financial Mistakes as Personal Failure
A mistake is information.
Learn from it.
Adjust.
Continue.
24. How to Create a Healthier Relationship With Money
A healthier relationship with money begins with changing the way you think about it.
Money is a resource.
Ultimately, Financial Stress and Mental Wellness are about creating a healthier relationship with money while protecting your emotional wellbeing and the lifestyle you want to build.
It can provide security.
It can create opportunities.
It can support experiences.
It can reduce certain forms of uncertainty.
But money is not a measurement of your worth.
Your income does not determine your value.
Your savings balance does not determine your character.
Your debt does not define your identity.
Your financial journey is simply one part of your life.
Create a system that helps you:
Know your numbers.
Plan your priorities.
Protect your future.
Enjoy your present responsibly.
Learn continuously.
Ask for help when necessary.
Avoid unnecessary comparison.
Protect your mental energy.
This balanced approach is at the heart of Financial Stress and Mental Wellness.
You are not trying to become obsessed with money.
You are trying to make money easier to manage.
25. Your 30-Day Financial Stress and Mental Wellness Challenge
Use the next 30 days to create greater financial awareness without turning money into an obsession.
Week 1: Awareness
Day 1: Write down your main financial priorities.
Day 2: Review your income.
Day 3: List your essential monthly expenses.
Day 4: Review recurring subscriptions.
Day 5: Look at one week of spending.
Day 6: Identify one financial stress trigger.
Day 7: Write down three financial habits you want to improve.
Week 2: Organization
Day 8: Create a simple spending plan.
Day 9: Organize upcoming bills.
Day 10: Review debt balances and payments.
Day 11: Identify unnecessary recurring expenses.
Day 12: Create or review a savings goal.
Day 13: Plan for one upcoming expense.
Day 14: Take a financial break and do something relaxing.
Week 3: Healthy Habits
Day 15: Pause before one nonessential purchase.
Day 16: Cook a meal at home.
Day 17: Choose a free or low-cost activity.
Day 18: Avoid financial comparison on social media.
Day 19: Spend 15 minutes learning about a financial topic.
Day 20: Have a healthy money conversation if appropriate.
Day 21: Review what is working.
Week 4: Confidence
Day 22: Set one realistic financial goal.
Day 23: Automate one useful financial action if appropriate.
Day 24: Review your spending priorities.
Day 25: Identify one money habit you want to stop.
Day 26: Identify one money habit you want to strengthen.
Day 27: Write down what financial security means to you.
Day 28: Take a break from financial content.
Day 29: Review your progress without judgment.
Day 30: Create your next 30-day financial wellness plan.
Remember that the challenge is not about becoming financially perfect.
It is about becoming more aware, intentional, and confident.
26. How KearnFit Supports Financial Stress and Mental Wellness
At KearnFit, we believe wellness is bigger than physical fitness.
Your mental fitness matters.
Your physical fitness matters.
Your emotional wellness matters.
Your financial wellness matters.
And your community matters.
Money habits can influence stress, lifestyle choices, relationships, confidence, and future opportunities.
That is why financial wellness belongs within a broader lifestyle approach.
Financial wellness is one part of a broader approach to wellbeing. Explore the four dimensions of fitness to understand how mental, physical, emotional, and financial wellness can work together to support a stronger, more balanced lifestyle.
If you want to understand how mental, physical, emotional, and financial wellness connect, explore the four dimensions of fitness and discover how these areas can work together to support a stronger, more balanced lifestyle.
Financial wellness does not mean chasing wealth at the expense of your health.
It means creating healthier financial habits that support the life you want to live.
That might mean becoming more aware of your spending.
It might mean building an emergency cushion.
It might mean setting financial goals.
It might mean reducing unnecessary pressure.
It might mean learning how to talk about money.
And sometimes it might mean asking for professional financial or mental health support.
There is no shame in needing help.
At KearnFit, the goal is sustainable progress.
A stronger lifestyle is built through small decisions repeated over time.
Visit www.kearnfit.com to explore the KearnFit approach and continue building a healthier life across every dimension of wellness.
27. Conclusion: Build Financial Confidence Without Sacrificing Your Wellbeing
Money matters.
But money should support your life, not control it.
Financial stress can affect your thoughts, emotions, relationships, sleep, lifestyle choices, and sense of security.
That is why Financial Stress and Mental Wellness deserve to be considered together.
You do not need to solve every financial challenge today.
A healthier approach to Financial Stress and Mental Wellness focuses on practical financial habits, emotional awareness, realistic goals, and a lifestyle that supports both your present wellbeing and future stability.
Start with awareness.
Understand where your money goes.
Create a realistic spending plan.
Build a financial cushion when possible.
Manage debt intentionally.
Set achievable goals.
Avoid unnecessary comparison.
Talk about money when appropriate.
Protect your mental energy.
And review your progress without judgment.
Remember that financial wellness is not simply about earning more.
It is about creating greater control, resilience, security, and freedom of choice.
Your financial journey will look different from everyone else’s.
Do not compare your starting point with someone else’s highlight reel.
Instead, focus on building habits that support your own values and circumstances.
A healthier financial life can create more space for the things that matter:
Your health.
Your relationships.
Your personal growth.
Your family.
Your goals.
Your experiences.
Your future.
And your peace of mind.
At KearnFit, we believe a stronger life is built by caring for the whole person.
Because true wellness is not only about how strong your body becomes.
It is also about how confidently you can manage your mind, emotions, relationships, finances, and everyday lifestyle.
Start where you are.
Make one healthier financial decision today.
Then make another tomorrow.
Small steps can create meaningful change.